We measure the financial structure of companies and report to the board and to the bank from the same data.
Our founders have assessed credit in banking and corporate finance since the 1990s. We offer that experience through a published methodology and our own platform that runs it.
Three readers, one measurement
The owner and the board read where the company stands today and where it is heading, the finance manager follows it day to day, and the bank finds a file that supports its credit assessment — all from the same records.
Owners and boards
- What you get
- A report on the company’s current financial health, its progress against the budget and how cash will develop over the coming months; weak points and recommendations.
- What we need
- Trial balance or financial statements, the budget if there is one; a conversation about the company’s business and plans.
Finance managers
- What you get
- Ratio analysis, budget against actuals, cash flow projection, and bank limit and risk tracking in one place; the board presentation and the bank file come from the same records.
- What we need
- Trial balance, credit and limit information, Findeks reports; you upload them to the platform or hand them to our analyst.
Banks and financial institutions
- What you get
- A file to support the bank’s credit assessment: the model rating and probability of default, the components of the rating, the credit committee decision, financial statements and the document list. Every file is prepared with the same methodology.
- What we need
- The consent and the financial documents of the company to be assessed.
Two outputs from the same data
Financial data is taken in once. The figures presented to the board and the figures given to the bank are the same.
Trial balance and financial statements
Annual and interim; with adjustments and data consistency checks
Board Financial Health Report
- Current financial position and ratios
- Budget against actuals
- Cash flow projection
- Weak points and recommendations
Bank Credit File
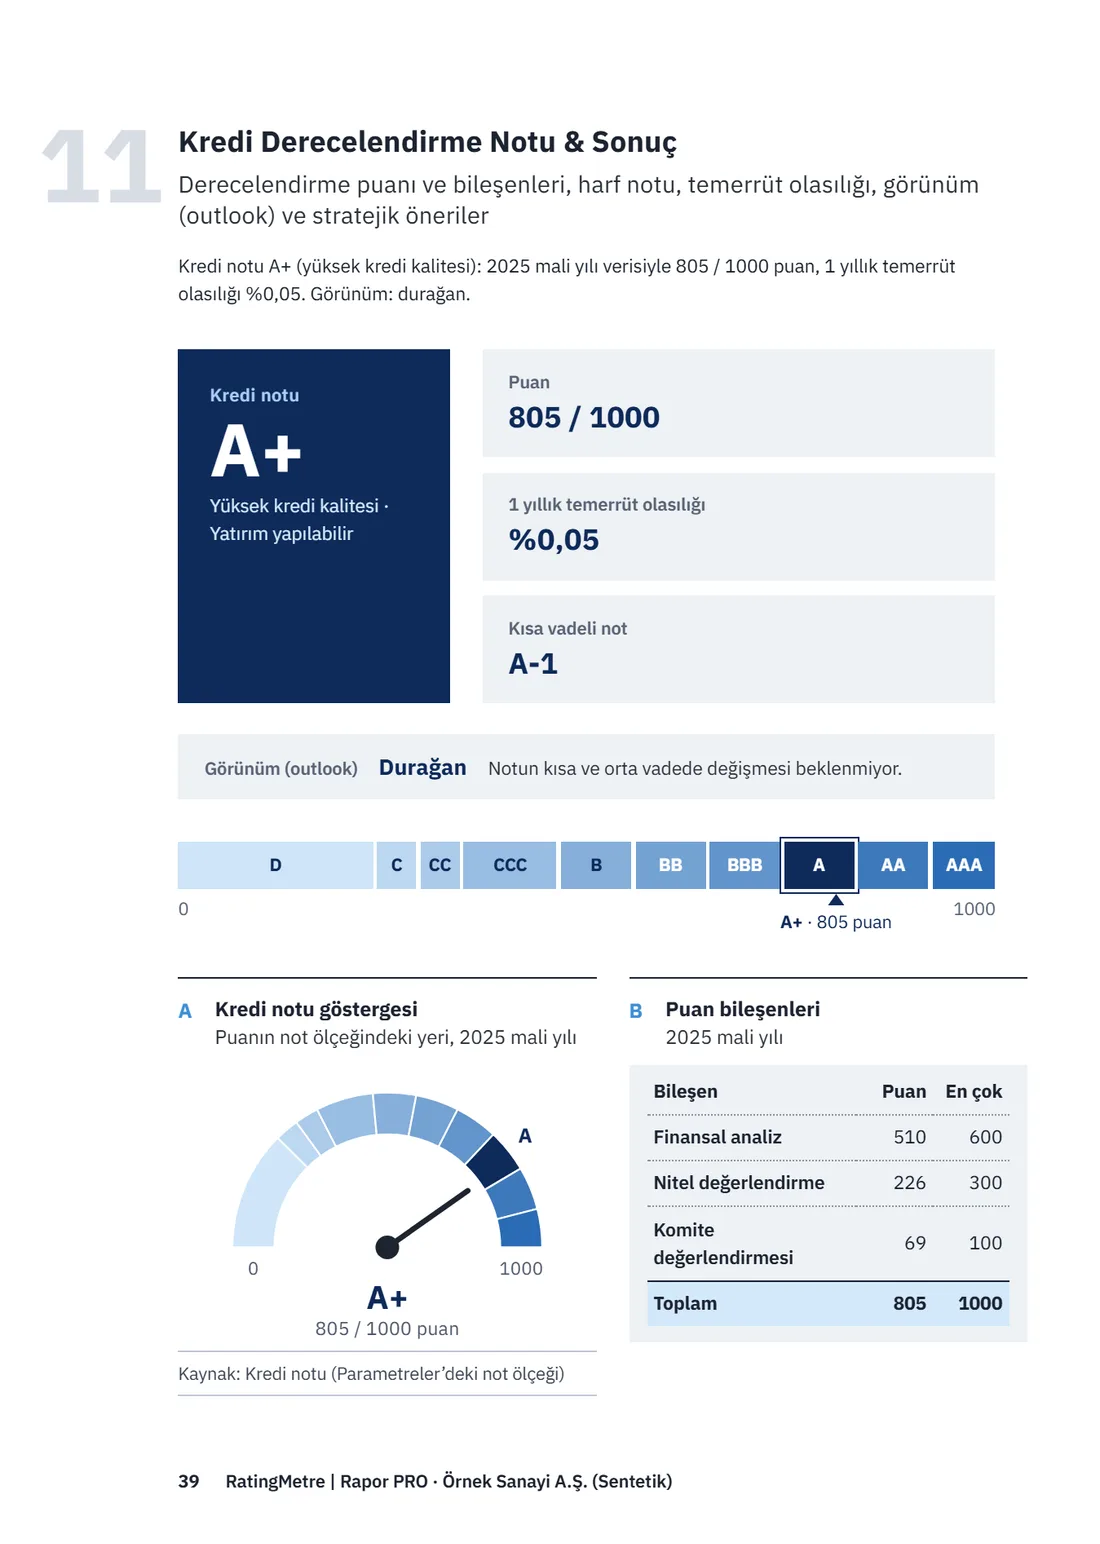
- Model rating and probability of default
- Components of the rating: financial, qualitative, committee
- Credit committee decision
- Financial statements and document list
We rate with a published methodology
The rating scale, the score structure, the ratio groups, the committee’s criteria and the rating ceilings are set out in our methodology; every change is recorded with its date.
Ratios from the financial statements, Altman Z’’ included
Questions on the sector, management, operations and bank relationships
Four criteria; the credit committee’s assessment
Total 1000 points · Rating model version 2, 19 October 2026Methodology
The credit committee approves the rating
The credit committee reviews the file prepared by the analyst, assesses it against four criteria and approves the rating.
Founders
- Mehmet GökdemirFounder
Banking and corporate finance since 1990: Osmanlı Bankası Inspection Board and head-office credit, Garanti Bankası regional credit (2003–2012), Deputy General Manager at Tam Faktoring (2012–2015).
- Olgun KoyuncuFounder
Banking and financial management since 1996: commercial portfolio management and branch management at Yapı Kredi (1998–2013), Branch Manager at Finansbank Çorlu (2013–2016); financial management advisory since 2016.
Credit committee
- Erkan SaygıCredit committee member
Banking and credit since 1997: Sümerbank Inspection Board, Oyak Bank credit risk monitoring, ING Bank SME credit allocation. Holds an individual credit rating licence.
- Hüseyin ErgutCredit committee member
Textile and food manufacturers since 1997; financial audit and management consulting since 2011. Holds an individual credit rating licence.
- Filiz KılıçCredit committee member
Accounting specialist, finance manager and independent auditor since 1993. Holds an individual credit rating licence.
How your financial data is protected
Measures in place on the platform today:
- Encryption in the browserFinancial statements and files sent to the platform are encrypted in the browser with AES-256, in addition to connection encryption; the server opens the content only while processing it.
- Masking of counterparty namesCustomer and supplier names are partly or fully hidden on screen depending on the user’s role; masking can also be chosen when a report is produced.
- Control of AI useThe AI used to read documents can be switched off per organisation; every call runs within a daily limit and is written to the audit log.
- Two-step sign-inTwo-step sign-in with an authenticator app; required for account owner and administrator roles, and available to other users.
- Role-based accessAccount owner, administrator, analyst and read-only roles; each user can carry out only the actions they are authorised for.
- Retention and deletionDeleted companies and documents can be restored during the retention period set by the organisation and are permanently deleted at its end; these actions are kept in the audit log.
Let us assess your company’s financial structure together
Çorlu, Tekirdağ, Türkiye · +90 850 217 83 33 · [email protected]